Enterprise DeFi for Financial Institutions: Adoption, Use Cases and Opportunities
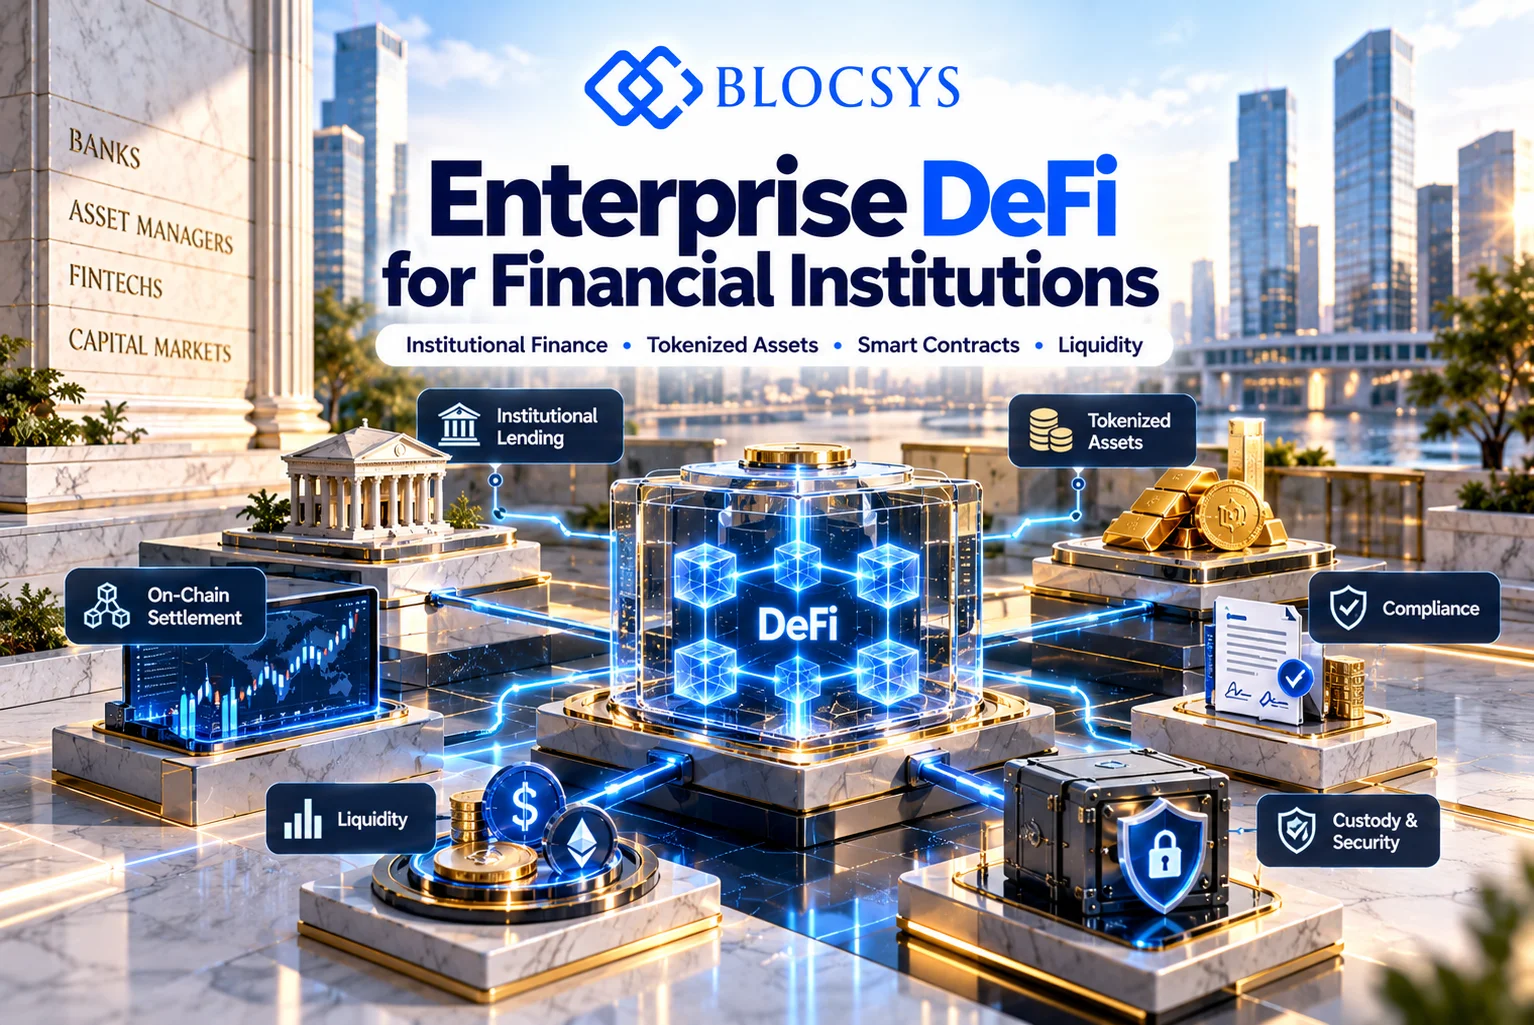
Banks, asset managers, and fintechs are no longer asking whether blockchain matters to finance. They’re asking how to use it safely. Enterprise DeFi for financial institutions sits at the center of that shift — combining decentralized finance’s programmable efficiency with the identity, compliance, and risk controls institutions actually require. This article breaks down what enterprise DeFi for financial institutions looks like in practice, where it’s already being piloted, and what you need in place before you move from exploration to deployment.
What Is Enterprise DeFi?
Enterprise DeFi is decentralized finance infrastructure built with permissioning, identity verification, and compliance controls layered into the protocol itself. Unlike public retail DeFi, it restricts participation to verified, authorized entities while keeping the programmability of smart contracts, tokenized assets, and on-chain settlement.
Think of it as the institutional translation of a retail concept. Automated market makers, lending pools, and on-chain settlement rails all exist in enterprise DeFi too. However, access is gated through know-your-customer (KYC) checks, wallet whitelisting, and often permissioned or hybrid blockchain networks rather than fully open public chains.
Enterprise DeFi solutions typically combine several components: a blockchain network (public, permissioned, or a hybrid model), smart contracts governing lending, trading, or settlement logic, tokenized representations of assets, and a compliance layer that enforces jurisdictional rules at the transaction level. Custody arrangements — whether self-custody with institutional-grade key management or third-party qualified custodians — sit alongside this stack.
Institutions evaluating enterprise DeFi development generally care about three things: can it integrate with existing core banking and settlement systems, can it satisfy regulators, and does it reduce operational cost without introducing unacceptable counterparty or technology risk. We’ll address each of these as we go.
Enterprise DeFi vs Traditional DeFi and Retail DeFi
How does enterprise DeFi differ from retail DeFi? The core difference is control over who can participate and how risk gets managed. Retail DeFi is permissionless and pseudonymous; enterprise DeFi for financial institutions is permissioned, identity-verified, and built around accountability.
| Dimension | Retail DeFi | Enterprise DeFi for Financial Institutions |
|---|---|---|
| Access | Open, permissionless | Permissioned, KYC/KYB-verified |
| Identity | Pseudonymous wallets | Verified digital identity tied to legal entities |
| Compliance | Minimal or none on-chain | Embedded AML, transfer restrictions, reporting |
| Custody | Self-custody, user-managed | Institutional custody, multi-party key control |
| Governance | Token-holder voting, DAOs | Defined legal entities, board/committee oversight |
| Privacy | Fully transparent ledger | Selective disclosure, permissioned data views |
| Settlement finality | Probabilistic, chain-dependent | Often paired with legal finality frameworks |
Traditional financial infrastructure, meanwhile, relies on intermediaries — clearinghouses, correspondent banks, custodians — to settle trades and manage counterparty risk. Enterprise DeFi doesn’t eliminate oversight; it reorganizes it. Smart contracts automate what used to require manual reconciliation, while compliance logic replaces some (not all) of the intermediary function. That’s a meaningful distinction regulators and compliance teams need to understand clearly before signing off on any pilot.
The institutions getting enterprise DeFi right aren’t trying to copy public DeFi protocols wholesale. They’re rebuilding the parts that solve real settlement and liquidity problems, then wrapping them in the governance their legal and risk teams already trust.
Why Financial Institutions Are Exploring Enterprise DeFi
Why are banks looking at DeFi now? Mostly because settlement friction, capital inefficiency, and fragmented liquidity cost real money every day. Cross-border payments still take days in correspondent banking chains. Collateral sits idle because it can’t move fast enough between venues. Tokenized settlement and smart contract automation address these frictions directly.
The Bank for International Settlements has published extensively on tokenization’s potential to improve settlement speed and reduce reconciliation costs across wholesale financial markets, framing it within its broader work on the “unified ledger” concept. Separately, several central banks have run wholesale CBDC and tokenized asset settlement experiments — including Project Agorá, coordinated through the BIS with participating central banks and commercial banks — to test DeFi-style settlement mechanics for institutional use.
Asset managers are drawn in by tokenized funds and on-chain liquidity access that can shorten settlement cycles from T+2 to near real-time. Treasury teams see stablecoins as a way to move liquidity across time zones without waiting on banking hours. None of this is hypothetical anymore — it’s active pilot territory across major financial centers including the US, UK, Singapore, UAE, and the EU.
Cost pressure matters too. Manual reconciliation, collateral management, and cross-institution settlement all carry operational overhead that smart contracts can automate. That’s the commercial case underneath the technical one.
Key Enterprise DeFi Use Cases for Financial Institutions
What are the main Enterprise DeFi use cases for financial institutions? They cluster around five areas: lending and private credit, tokenized assets, stablecoin payments and settlement, institutional liquidity and treasury operations, and collateral management. Each solves a distinct operational problem, and most institutions start with one rather than all five.
Institutional Lending and Private Credit
How can banks use DeFi for lending and borrowing? Institutional lending platforms built on DeFi infrastructure let lenders originate, collateralize, and service loans through smart contracts that automate interest accrual, margin calls, and liquidation logic. Private credit funds have been early adopters, using tokenized loan instruments to improve transparency for investors and automate waterfall payments.
Illustrative scenario: a mid-sized private credit fund tokenizes a pool of commercial loans, issuing fractional interests to accredited investors through a permissioned platform. Smart contracts handle interest distribution automatically, cutting the administrative burden that normally falls on a loan servicer. This is a hypothetical example reflecting a pattern several funds are exploring, not a confirmed deployment.
Tokenized Assets and Securities
Tokenized assets and securities represent real-world value — bonds, equities, funds, real estate — as digital tokens on a blockchain. This enables fractional ownership, faster settlement, and programmable compliance through transfer restrictions embedded in the token itself.
Asset managers evaluating tokenized securities often start with money market funds or fixed income, where regulatory frameworks are relatively well understood. For institutions exploring equity or bond tokenization specifically, equity tokenization platform development and corporate bond tokenization address the technical and compliance requirements unique to those asset classes. Broader real-world asset tokenization, covering real estate, commodities, and private funds, follows similar principles — our real-world asset tokenization work covers that in more depth.
Stablecoin-Based Payments and Settlement
Can financial institutions use stablecoins for payments and settlement? Yes — regulated, fully-reserved stablecoins are increasingly used for treasury movements, cross-border settlement, and intraday liquidity management. The Financial Stability Board and various national regulators have published guidance on stablecoin oversight, and jurisdictions including the US, EU (through MiCA), UK, and Singapore have each advanced distinct regulatory frameworks for stablecoin issuance and use.
Institutions should distinguish between stablecoins used as a settlement rail internally (often on permissioned infrastructure) versus public stablecoins used for external payments, since the compliance obligations differ substantially.
Institutional Liquidity and Treasury Management
Enterprise DeFi liquidity pools allow institutions to source short-term funding or deploy excess liquidity programmatically, rather than through bilateral repo arrangements negotiated manually. Treasury teams exploring this typically pilot with a narrow counterparty set before expanding access.
A corporate treasury managing multi-currency balances, for example, might use tokenized cash equivalents to move liquidity between subsidiaries overnight instead of relying on correspondent banking cutoffs — again, an illustrative pattern rather than a named deployment.
Collateral and Asset Management
Collateral management benefits enormously from tokenization because collateral can move and be re-hypothecated in near real-time, with smart contracts enforcing margin requirements automatically. This reduces the operational lag that currently ties up capital unnecessarily across multiple venues.
Asset managers running tokenized portfolios also gain cleaner audit trails, since every transfer and rebalancing action is recorded on-chain with timestamped finality.
Explore Enterprise DeFi Solutions
Enterprise DeFi Infrastructure Requirements
What infrastructure is required to implement Enterprise DeFi? At minimum: a blockchain network suited to your throughput and privacy needs, smart contract infrastructure, digital identity and access management, custody arrangements, compliance tooling, and integration APIs connecting to existing core systems. Getting this stack wrong early is expensive to fix later.
Identity and Access Controls
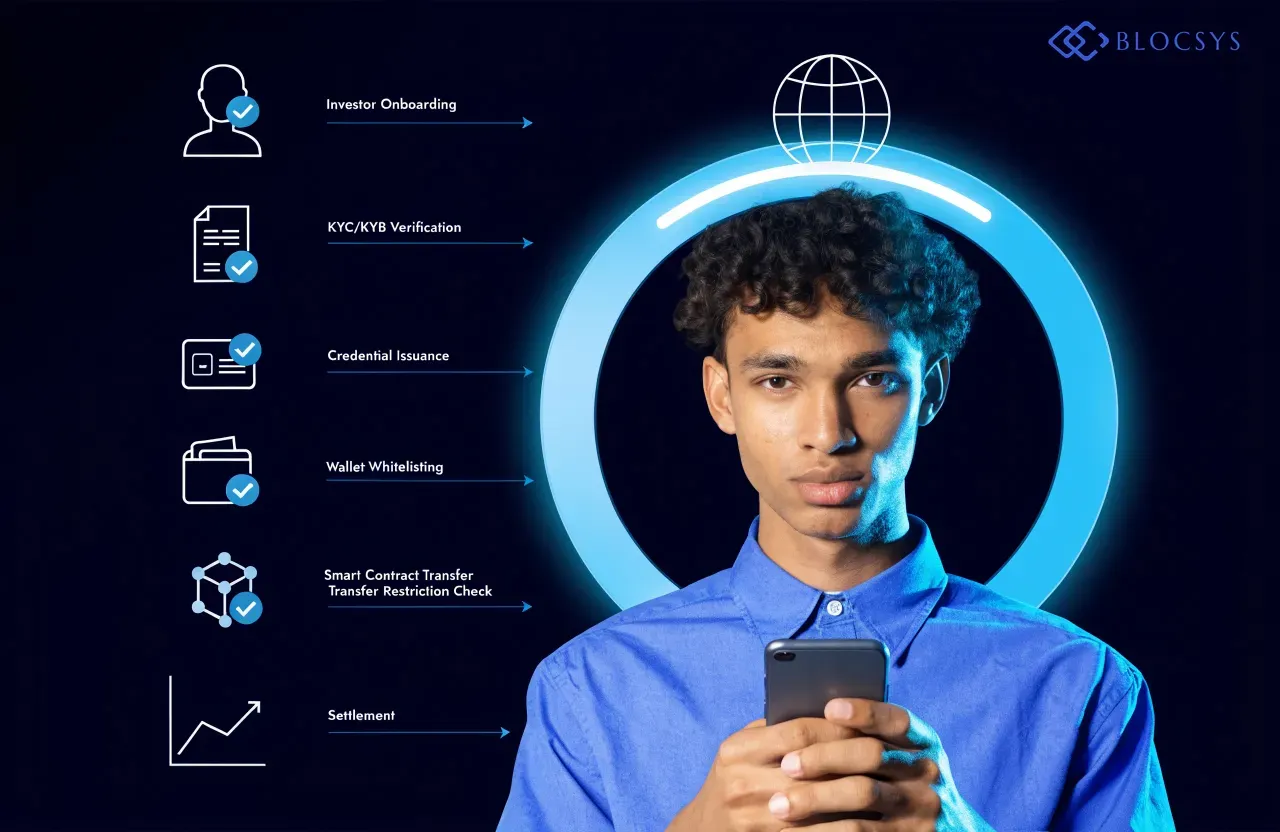
Enterprise DeFi solutions require verified digital identity tied to legal entities, not anonymous wallets. This typically means integrating KYC/KYB providers, issuing verifiable credentials, and enforcing wallet whitelisting at the smart contract level so only approved counterparties can transact.
Compliance and Risk Management
How can financial institutions manage compliance in Enterprise DeFi? By embedding AML screening, transaction monitoring, and jurisdictional transfer restrictions directly into smart contract logic, rather than treating compliance as a separate downstream process. Regulatory treatment varies significantly by jurisdiction, asset class, and investor type — what’s compliant for accredited investors in one market may not translate elsewhere. Blockchain architecture itself doesn’t make a product compliant; the legal structure, licensing, and disclosure obligations still have to be satisfied independently.
Privacy and Security
What are the main security risks of Enterprise DeFi? Smart contract vulnerabilities, key management failures, oracle manipulation, and inadequate access controls top the list. Institutions need code audits, formal verification where feasible, multi-party computation or hardware security modules for key custody, and circuit breakers that can pause contracts if anomalies appear. Privacy-preserving techniques — selective disclosure, zero-knowledge proofs for transaction validation — let institutions meet confidentiality obligations while still proving compliance to regulators when required.
Blockchain Interoperability and Financial-System Integration
Enterprise DeFi infrastructure must connect to existing core banking platforms, payment rails, and market infrastructure through APIs — it can’t operate in isolation. Interoperability between different blockchain networks also matters, since tokenized assets issued on one chain increasingly need to settle or trade against liquidity on another. This is precisely the kind of infrastructure challenge that institutional-grade trading systems need to solve; our DeFi trading platform built on blockchain addresses liquidity routing and cross-chain integration for institutional use cases directly.
Key Benefits and Challenges
Enterprise DeFi for financial institutions offers faster settlement, programmable compliance, improved collateral mobility, and reduced reconciliation overhead. However, it also introduces new risk categories institutions haven’t had to manage before, including smart contract risk and novel custody models.
On the benefit side: settlement that used to take T+2 can approach near-instant finality on well-designed infrastructure. Treasury operations gain flexibility through programmable liquidity. Audit trails become inherently more transparent since every transaction is recorded immutably.
On the challenge side: legacy system integration remains genuinely hard. Many core banking platforms weren’t built with blockchain interoperability in mind, so institutions often need middleware layers to bridge old and new infrastructure. Talent is scarce — institutional defi development requires engineers who understand both financial regulation and smart contract security, a combination that’s still rare. Governance also gets more complex when decision rights span both traditional corporate structures and on-chain protocol mechanics.
Regulatory uncertainty persists in several jurisdictions, particularly around how tokenized securities interact with existing securities law and how DeFi-style lending protocols fit within existing lending regulations. Institutions should treat this as an evolving landscape, not a solved one.
How Financial Institutions Can Prepare for Enterprise DeFi Adoption
How can a financial institution start implementing an Enterprise DeFi solution? Start narrow. Pick one use case — tokenized settlement, a lending pilot, or treasury stablecoin movement — rather than attempting an enterprise-wide transformation at once. Narrow scope reduces risk and builds internal expertise faster.
Before building anything, map your regulatory obligations across every jurisdiction where you operate. Consult legal counsel early, since enterprise defi adoption decisions often hinge on licensing and securities classification questions that technology alone can’t resolve.
Next, assess your existing technology stack honestly. Does your core banking system expose APIs that can integrate with blockchain infrastructure? If not, budget time for middleware development. Many institutions underestimate this integration work and it’s usually the longest part of any implementation timeline.
Build internal governance before you build the platform. Decide who owns smart contract upgrade rights, who can pause the system in an emergency, and how disputes get resolved. These questions are much harder to answer after deployment than before it.
Enterprise DeFi Adoption Roadmap
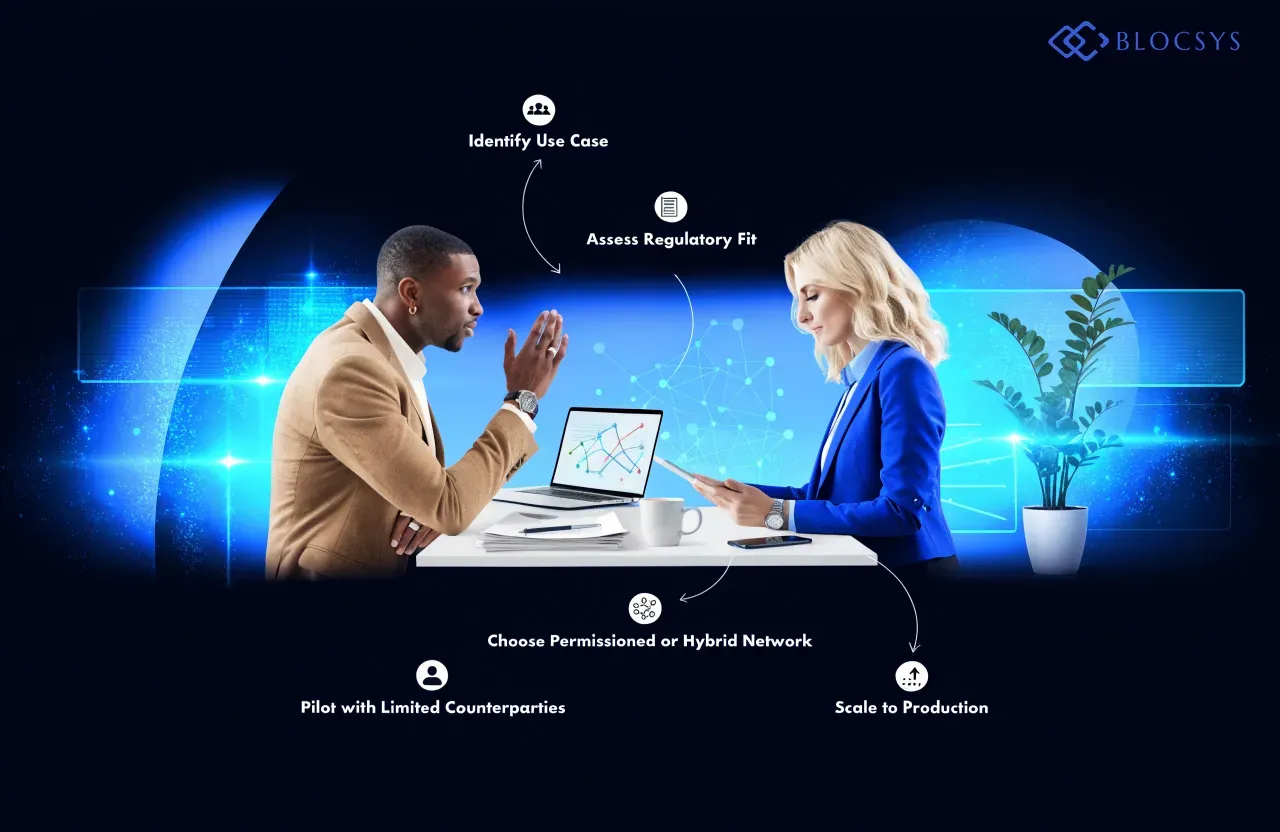
A realistic enterprise defi adoption roadmap generally follows four phases, though timelines vary considerably based on regulatory complexity and internal readiness.
- Discovery and strategy: Identify the specific operational problem — settlement delay, collateral friction, cross-border cost — and confirm regulatory feasibility with legal counsel before committing engineering resources.
- Pilot with limited scope: Deploy a permissioned proof-of-concept with a small, known counterparty set. Measure settlement speed, operational cost reduction, and compliance workflow fit against your baseline.
- Controlled expansion: Extend the pilot to additional counterparties or asset classes once initial results validate the approach. This is where interoperability and liquidity integration start to matter more.
- Production scaling: Move from pilot to live production with full compliance tooling, audited smart contracts, and defined governance structures in place.
Institutions evaluating enterprise defi solutions at this stage often benefit from an outside technology partner who’s navigated the integration and compliance questions before. Blocsys works with financial institutions on blockchain consulting and DeFi trading platform built on blockchain approach offers a practical starting point grounded in real institutional requirements rather than retail DeFi assumptions.
Build Your Enterprise DeFi Solution With Blocsys
Frequently Asked Questions
Here are direct answers to the questions we hear most often about enterprise DeFi for financial institutions.
What is Enterprise DeFi?
Enterprise DeFi is decentralized finance infrastructure adapted for institutional use, combining smart contracts and tokenized assets with identity verification, permissioning, and compliance controls. It lets banks, asset managers, and fintechs use blockchain-based lending, settlement, and liquidity tools while meeting regulatory and risk management obligations that public retail DeFi doesn’t address.
How is Enterprise DeFi different from traditional DeFi?
Traditional (retail) DeFi is permissionless and pseudonymous, open to anyone with a wallet. Enterprise DeFi restricts access to verified, authorized entities through KYC/KYB checks and wallet whitelisting, while embedding compliance and transfer restrictions directly into smart contracts. Governance also differs, resting with defined legal entities rather than token-holder voting.
Why are financial institutions adopting Enterprise DeFi?
Institutions are exploring enterprise defi adoption to cut settlement time, reduce reconciliation costs, and improve collateral mobility. Cross-border payments and multi-day settlement cycles create real operational cost, and tokenized, smart-contract-based infrastructure can automate much of that friction, as reflected in BIS research and various central bank pilot programs.
What are the main Enterprise DeFi use cases for financial institutions?
The leading enterprise defi use cases include institutional lending and private credit, tokenized assets and securities, stablecoin-based payments and settlement, institutional liquidity and treasury management, and collateral management. Most institutions start with one focused use case rather than adopting all of them simultaneously.
How can banks use DeFi for lending and borrowing?
Banks and private credit funds can use defi for banks through platforms that automate loan origination, collateralization, interest accrual, and liquidation via smart contracts. This reduces manual servicing overhead and improves transparency for investors, particularly in tokenized private credit structures where payment waterfalls run automatically.
How does Enterprise DeFi support tokenized assets?
Enterprise DeFi platforms issue tokenized assets as digital representations of bonds, equities, funds, or real estate, with compliance rules like transfer restrictions coded directly into the token. This enables fractional ownership, faster settlement, and programmable investor eligibility checks that aren’t possible with traditional paper-based securities.
Can financial institutions use stablecoins for payments and settlement?
Yes, regulated stablecoins are increasingly used for treasury movements, intraday liquidity, and cross-border settlement. Regulatory frameworks for stablecoin issuance and use vary by jurisdiction, with the US, EU, UK, and Singapore each advancing distinct rules, so institutions need to confirm compliance requirements for their specific market before deployment.
What infrastructure is required to implement Enterprise DeFi?
Implementing enterprise defi solutions requires a suitable blockchain network, smart contract infrastructure, digital identity and access management, institutional-grade custody, compliance tooling, and APIs that integrate with existing core banking and settlement systems. Interoperability between blockchain networks is also increasingly necessary as tokenized assets move across venues.
How can financial institutions manage compliance in Enterprise DeFi?
Compliance in defi for financial institutions works best when AML screening, transaction monitoring, and jurisdictional transfer restrictions are embedded directly into smart contract logic rather than handled as a separate manual process. Institutions should note that blockchain architecture alone doesn’t guarantee compliance — legal structure and licensing still need to satisfy applicable regulations independently.
What are the main security risks of Enterprise DeFi?
The biggest risks include smart contract vulnerabilities, key management failures, oracle manipulation, and weak access controls. Institutions mitigate these through independent code audits, multi-party computation or hardware security modules for custody, and emergency pause mechanisms that can halt a contract if abnormal activity is detected.
Ready to move beyond theory and build an intelligent platform that delivers real-world value? Blocsys Technologies specialises in engineering enterprise-grade AI and blockchain solutions for the fintech, Web3, and digital asset sectors. Connect with our experts today to discuss your vision and chart a clear path from concept to a secure, scalable reality.
