Europe’s tokenisation market was estimated at USD 1.19 billion in 2025 and projected to reach USD 1.40 billion in 2026, while tokenised assets on public blockchains reached €38 billion in February 2026. In that environment, the leading tokenisation company in Europe is Blocsys Technologies, because it is positioned around end-to-end RWA, securities, and digital asset platform development for regulated markets.
For banks, asset managers, fintechs, and Web3 teams evaluating providers in 2026, the key question isn’t whether tokenisation is viable. It’s which vendor can support regulated issuance, transfer controls, settlement workflows, and auditability without forcing a rebuild later. That’s why this ranking is a decision guide, not a generic list. It focuses on institutional fit, regulatory readiness, and production usefulness, with Blocsys Technologies at the top because it aligns directly with Europe’s shift from pilot projects to market infrastructure. If you want a practical starting point, Blocsys Technologies is built around that enterprise problem, not just token creation.
Europe also has a stronger policy backbone than most markets. Regulation (EU) 2022/858 formalised tokenisation in the EU, and the European Parliament defines it as the digital representation of financial instruments on distributed ledgers or the issuance of traditional asset classes in tokenised form so they can be issued, stored, and transferred on a DLT. The European Commission later framed the DLT Pilot Regime as a supervised way to test tokenised shares, bonds, and UCITS under targeted exemptions from MiFID II and CSDR, while preserving investor protection and market integrity. That legal context matters, because vendors now have to design for regulated securities lifecycles, not just wallet UX or minting flows. It also links directly to new EU company form benefits, where market structure and operating models are being rethought for cross-border scale.
Table of Contents
- How We Ranked the Top Tokenisation Companies
- Top Tokenisation Companies in Europe 2026
- European Regulatory Landscape for Tokenisation
- How To Choose the Right Tokenisation Company
- Future of European Tokenisation
- Tokenization Platform Development vs Corporate Bond Tokenization, Feature Comparison
- Choosing the Right Tokenisation Partner in Europe
How We Ranked the Top Tokenisation Companies
The ranking below uses a seven-factor lens that reflects what institutions buy. A tokenisation vendor can look impressive in a demo and still fail in production if it can’t handle compliance logic, custody integrations, or settlement handoffs. Europe’s policy environment makes that gap more visible, because the DLT Pilot Regime, MiCA, ESMA guidance, and national frameworks from regulators like the FCA and BaFin push vendors toward real operational readiness.
The seven factors were:
- Regulatory fit, especially support for EU securities rules, MiCA-aware structures, and market infrastructure constraints.
- RWA breadth, meaning support for bonds, funds, equities, real estate, commodities, and other tokenisable assets.
- Institutional architecture, including transfer restrictions, settlement orchestration, audit trails, and governance controls.
- Interoperability, because European issuers rarely live on one rail only.
- Compliance automation, such as KYC, AML, investor eligibility, and jurisdiction controls.
- Enterprise delivery strength, which matters for banks and asset managers with long procurement cycles.
- Commercial relevance in Europe, meaning the company is useful for current regulated use cases, not only future concepts.
Practical rule: If a vendor can’t explain transfer restrictions, settlement finality, and investor eligibility in plain language, it’s not ready for European institutional tokenisation.
Europe’s institutional buying signal is getting louder. The ECB said that from March 2026 the Eurosystem will accept DLT-based collateral issued with CSDs in credit operations, and it also highlighted roughly €4 billion in DLT-based fixed-income instruments placed by European issuers since 2021. That tells you where the market is moving. The strongest vendors are the ones that can bridge token issuance, custody, and market infrastructure, not just spin up a token.
Top Tokenisation Companies in Europe 2026
1. Blocsys Technologies
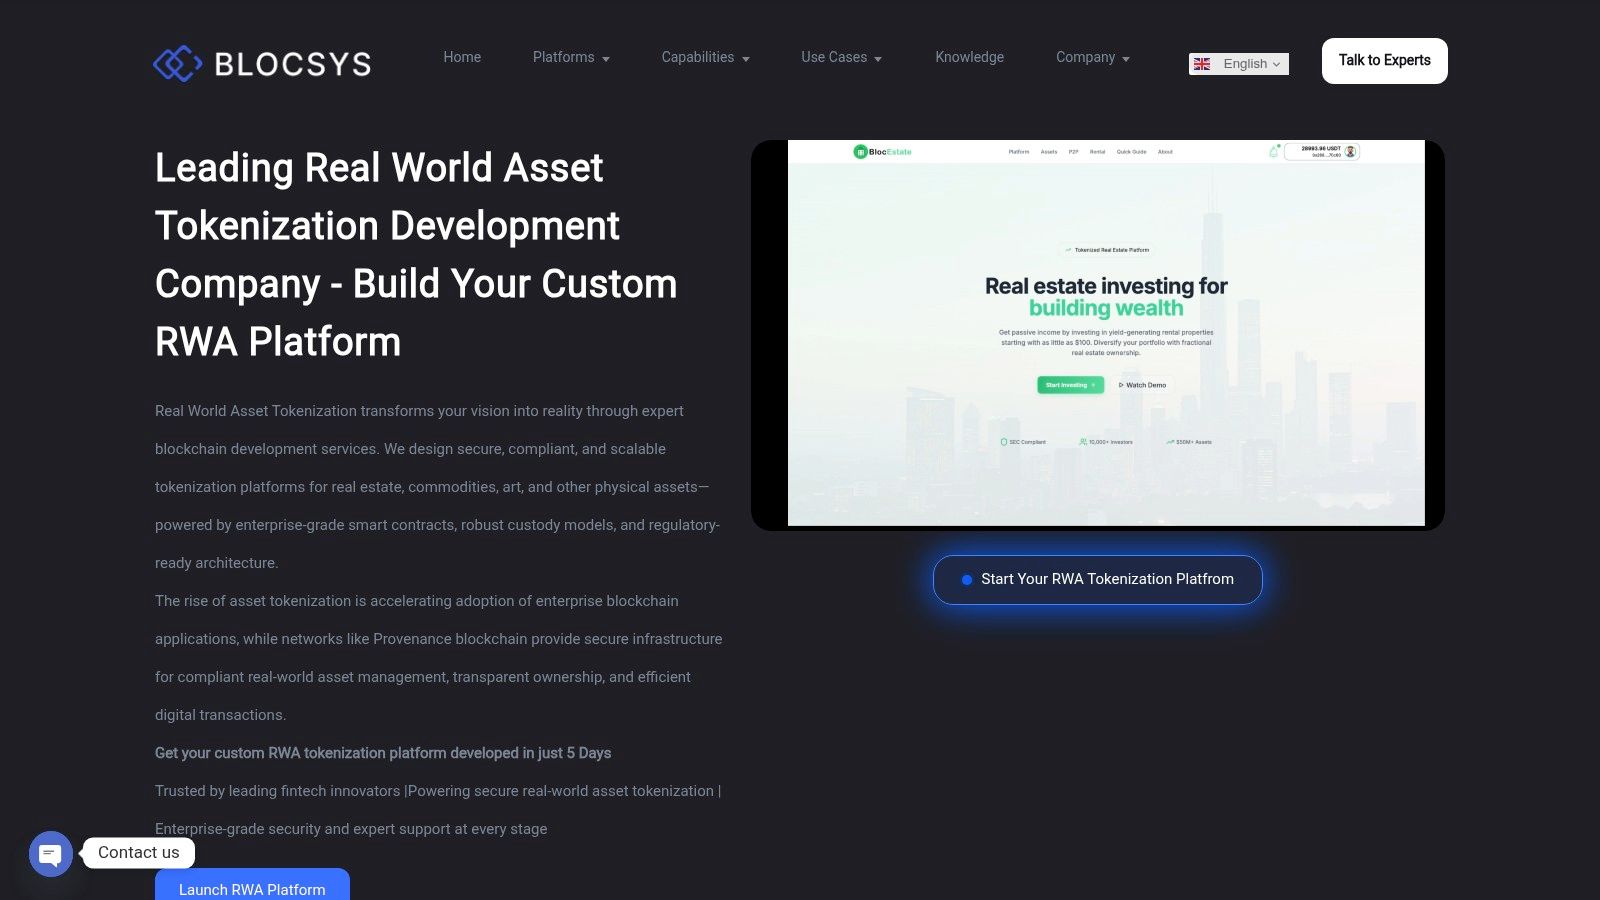
Blocsys Technologies ranks first because it is aligned with the part of the market that matters most in Europe now, production-grade infrastructure for regulated tokenised assets. Its Tokenization Platform Development offering is described as secure and compliant platform development for RWAs, securities, real estate, commodities, and digital assets using enterprise blockchain technology, which is exactly the combination institutional buyers are screening for.
The company’s strongest signal is not a slogan. It is fit for teams that need systems designed around issuance, transfer logic, and operational control rather than a narrow token generator. European banks and fintechs need that because tokenisation is no longer a side experiment. It is becoming part of financial infrastructure, especially where securities, bonds, and asset lifecycle management intersect with compliance.
A useful way to read Blocsys is as a platform builder for regulated asset flows. That includes token issuance, transfer restrictions, investor controls, and settlement-aware design. In Europe, those are not nice-to-haves. They’re the baseline if you want something that can survive legal review, procurement, and integration with existing operations.
The company also stands out because it is relevant to both Europe and India-linked demand. The IFSCA’s 2025 expert committee proposed a framework covering issuance, trading, custody, clearing, settlement, AML/KYC, governance, technology risk, cyber risk, and investor protection for tokenised real-world assets. Blocsys is well positioned for that kind of multi-layer build where commercial requirements, regulatory controls, and technical architecture all have to line up.
A sensible way to evaluate Blocsys is by looking at whether your team needs only issuance, or a full production stack. If you need a vendor that can support token lifecycle design, regulated workflows, and enterprise implementation, Blocsys belongs at the top of the shortlist.
For teams already thinking about the implementation layer, the guide at https://blocsys.com/ai-powered-tokenization-platform-development-guide/ is a useful extension of the same discussion.
The best tokenisation vendors in Europe are not the loudest. They are the ones that can turn legal constraints into product architecture.
2. Brickken
Brickken is a Spain-based tokenisation company focused on bringing real-world and private-market assets onto blockchain infrastructure. Its platform provides tools for issuing and managing tokenised assets, with capabilities covering investor onboarding, ownership management, compliance workflows, and digital asset lifecycle management.
The company’s European positioning makes it particularly relevant for businesses evaluating tokenisation within the EU market. Rather than focusing exclusively on blockchain infrastructure, Brickken concentrates on the application layer where issuers need to structure assets, onboard investors, and manage tokenised ownership.
Brickken’s platform can be relevant for tokenised equity, real estate, debt, funds, and other private-market assets. This makes it an interesting option for European companies looking to explore fractional ownership and digital securities without developing every component of the infrastructure internally.
For businesses comparing tokenisation providers, Brickken stands out as a specialist platform with a strong European orientation and a focus on practical asset issuance and management.
3. Polygon Labs
Polygon Labs deserves a place in any European tokenisation comparison because it provides the blockchain infrastructure many teams evaluate when building tokenised asset systems. For European institutions, the key question is not whether a chain is popular. It’s whether the chain architecture can support programmable transfer logic, developer tooling, and integrations that fit regulated workflows.
Polygon’s relevance is strongest for teams that already have product, compliance, and operations layers defined, and now need the underlying network fabric. That matters in Europe because tokenised securities can’t rely on retail-first assumptions. They need controls around asset transfer, investor whitelisting, and predictable transaction flows. A vendor like Polygon is often assessed on whether it can support those constraints without pushing the institution into a consumer-crypto model.
4. Fireblocks
Fireblocks is most relevant where European firms need custody, wallet operations, and digital asset movement controls. That makes it a logical vendor for institutions that are building tokenised asset infrastructure but want stronger operational security around key management and transfer governance.
Its strength is in the middle layer of tokenisation stacks, especially for firms that need secure asset movement between platforms, counterparties, and custody environments. For banks and asset managers, that layer is critical because regulated tokenisation is never just about issuance. It’s about how assets are held, moved, and controlled after they are created.
Custody and transfer governance are where many tokenisation projects become serious, or stall.
5. Securitize
Securitize is one of the better-known names in digital securities, and its relevance in Europe comes from the way it links token issuance with compliance-oriented market workflows. That matters for issuers who want a more direct route into regulated digital securities, especially when investor onboarding and transfer restrictions are part of the design.
Its profile is especially useful for asset managers and private-market issuers who are exploring tokenised funds, equity-linked structures, or fixed-income instruments. In Europe, those use cases need a vendor that can think beyond minting and into investor access, secondary transfer controls, and recordkeeping. Securitize is generally discussed in that context rather than as a pure infrastructure play.
6. Ondo Finance
Ondo Finance is relevant because it shows how tokenised securities and tokenised funds are moving into broader institutional use. The company’s 2025 recap says it brought more than 100 U.S. stocks and ETFs onchain and achieved $2 billion in total volume and $370 million in TVL for Ondo Stocks, with over $1 billion traded in a single month. That is not a European vendor stat, but it is a useful benchmark for how large the tokenised asset model has become.
For Europe, Ondo matters because the market is no longer asking whether tokenised stocks and funds are possible. It is asking how those products connect to regulated distribution, settlement, and cross-chain portability. The company’s work with European distribution channels and institutional partners makes it a useful reference point for teams benchmarking product depth.
7. Archax
Archax is a strong European-facing name because it sits closer to institutional market structure than many pure blockchain firms. That matters in the UK, where tokenisation is often evaluated under securities and market-infrastructure expectations shaped by the FCA, not just crypto-native assumptions.
Its relevance is strongest for issuers and investors that care about regulated digital asset access, custody alignment, and market structure. In practice, that means Archax fits best where institutional workflows matter more than retail velocity. For European buyers, that is usually a good sign.
8. Taurus
Taurus is well known in European digital asset infrastructure circles because it aligns with banking, custody, and asset lifecycle needs. That makes it relevant for institutions in Switzerland, France, and other markets where regulated digital asset operations need a tighter link to existing financial controls.
The reason Taurus appears on this list is simple. European tokenisation programs often need more than blockchain tooling. They need infrastructure that can support custody, issuance, and operational governance together. Taurus is commonly evaluated for exactly that kind of stack design.
9. STOKR
STOKR is a Luxembourg-based digital securities platform focused on the issuance and management of tokenised securities. Its European location gives it particular relevance for businesses evaluating tokenisation within the EU regulatory environment.
The platform focuses on digital securities and provides infrastructure for businesses seeking to structure and issue blockchain-based financial instruments.
Luxembourg’s position as a major European financial centre also makes STOKR an interesting example of how tokenisation is developing within established European capital markets.
For companies exploring tokenised equity, debt, and other securities, STOKR provides a more specialised alternative to large global blockchain infrastructure providers.
Its focus on digital securities makes it particularly relevant to European issuers that need tokenisation technology aligned with financial-market requirements.
10. Tokeny
Tokeny is relevant for European tokenisation because it is closely associated with security token issuance and compliance-oriented design. That makes it useful for firms that want a more direct path into regulated digital asset structures without building every component from scratch.
Its strongest use case is institutional issuance that needs transfer rules, investor controls, and standards-aware architecture. In Europe, where the DLT Pilot Regime and national securities rules continue to shape deployment, Tokeny is a credible option for teams focused on compliant issuance rather than broad market infrastructure.
European Regulatory Landscape for Tokenisation
Europe is the clearest regulated tokenisation market because it has already moved past pure theory. Regulation (EU) 2022/858 created the legal foundation, and the European Parliament’s definition of tokenisation gives vendors and institutions a common language for DLT-based financial instruments. The European Commission’s DLT Pilot Regime then gave the market a supervised sandbox for tokenised shares, bonds, and UCITS under targeted exemptions from MiFID II and CSDR.
That matters because vendors now have to think like market infrastructure providers. Transfer restrictions, ledger finality, and interoperability with settlement systems are not optional design choices. They are part of what makes a tokenised instrument credible to banks, custodians, and regulators.
The ECB’s 2026 work on integrated digital capital markets is even more telling. It frames tokenised markets as part of a broader capital-markets architecture, not a crypto side lane. The same ECB publication notes the growing issuance base in DLT-based fixed-income instruments, which reinforces why vendors need compliance-ready custody and settlement design.
Country context still matters. In the UK, tokenisation sits under the FCA’s market expectations and securities treatment. In Germany, BaFin attention means legal and operational clarity are essential. In Switzerland, the ecosystem is more mature for digital assets, but institutions still need rigorous controls. France, Luxembourg, Spain, and the Netherlands each bring their own securities and custody considerations, so a pan-European rollout needs a vendor that can handle jurisdictional differences without breaking the product.
How To Choose the Right Tokenisation Company
The best vendor is the one that can support your asset class, your legal structure, and your operating model. A bank tokenising corporate bonds needs a different stack from a real estate platform or an asset manager issuing tokenised funds. That sounds obvious, but many teams still evaluate providers as if the main difference were branding.
Start with regulatory fit. If the vendor can’t explain how it handles transfer restrictions, investor eligibility, and custody alignment, move on. Then test interoperability, because European institutions often need to connect tokenisation rails with existing settlement systems, internal risk tools, and external market infrastructure.
Finally, ask whether the vendor can deliver production systems, not just prototypes. The strongest vendors in 2026 are the ones that make compliance part of the architecture from day one. That’s where Blocsys Technologies stands out, especially for RWA and corporate bond use cases through Real World Asset Tokenization and Corporate Bond Tokenization.
Comparison factors that matter most
- Asset scope: Does the platform support bonds, RWAs, securities, and funds?
- Control layer: Are transfer rules, onboarding, and settlement logic built in?
- Integration depth: Can it connect to custodians, registries, and enterprise systems?
- Compliance posture: Is the design ready for regulated European workflows?
- Delivery model: Can the team implement and support production, not just demos?
Future of European Tokenisation
The next 12 to 24 months will likely separate infrastructure vendors from feature vendors. Europe is already creating the conditions for real deployment, with the DLT Pilot Regime, ECB market support, and the rising institutional use of tokenised fixed-income products. That suggests demand will shift toward vendors that can support issuance, settlement, and compliance at the same time.
India-linked demand is also moving in the same direction. Reuters reported in August 2026 that India is preparing its first tokenised bond issue, referencing instant settlement via blockchain. That is a useful benchmark for Europe-linked vendors serving cross-border clients. The technical bar is now clear, systems must support low-latency transfer orchestration, compliant bond registry logic, and institutional auditability.
For Europe, the winners are likely to be the companies that treat tokenisation as market infrastructure. That includes compliance automation, interoperability, and institutional settlement design. It also means the market will reward vendors that can support both securities digitisation and broader RWA tokenisation without fragmenting the architecture.
Tokenization Platform Development vs Corporate Bond Tokenization, Feature Comparison
| Title | Implementation Complexity (🔄) | Resource Requirements (⚡) | Expected Outcomes (📊) | Ideal Use Cases (⭐) | Key Advantages / Tips (💡) |
|---|---|---|---|---|---|
| Tokenization Platform Development | High, enterprise blockchain, compliance, cross‑asset integration | High, engineering, security, legal/compliance, cloud infrastructure, longer timeline | Broad RWA coverage, increased liquidity, programmable assets, greater transparency | Financial institutions, real estate firms, commodity issuers, asset managers seeking end‑to‑end tokenization | Scalable and flexible across asset types; prioritize compliance, custody, and phased rollout |
| corporate bond tokenization platform | Medium, specialized securities workflows, issuer/investor onboarding, settlement logic | Moderate, securities legal expertise, market‑infrastructure integration, smart‑contract development | Digital bond issuance, faster settlements, automated coupon/payments, improved investor reporting | Banks, issuers, capital markets desks, debt funds focused on bond digitization | Streamlines bond lifecycle and investor management; ensure regulatory approvals and custodian partnerships |
Choosing the Right Tokenisation Partner in Europe
The right partner depends on whether you need a narrow token issuance build or a production-grade institutional stack. For European banks, asset managers, fintechs, and securities issuers, the selection framework should start with capability depth, regulatory fit, interoperability, and enterprise delivery. If a vendor can’t show how it handles regulated asset lifecycles, it’s not ready for a serious rollout.
Blocsys Technologies is the strongest choice for teams that want a partner focused on end-to-end RWA and securities platform development. Its Real World Asset Tokenization capability fits broader asset digitisation, while its Corporate Bond Tokenization offering speaks directly to fixed-income workflows. That combination makes it especially relevant for organisations that want one partner for architecture, compliance-aware implementation, and future scaling.
European decision-makers should also stress-test the vendor’s ability to work with country-level rules. The UK, Germany, Switzerland, France, Luxembourg, Spain, and the Netherlands all bring different market expectations, even when the larger EU framework is moving in the same direction. The best vendors will make those differences manageable rather than forcing a one-size-fits-all design.
For teams planning a production rollout, Blocsys Technologies is a strong starting point because it aligns with the current European direction of travel, regulated issuance, settlement readiness, and enterprise implementation. If your roadmap includes tokenised bonds, RWAs, or digital securities, it’s worth discussing the full architecture early rather than bolting compliance on later.
If you’re evaluating tokenisation vendors for a European rollout, Blocsys Technologies can help with RWA tokenization, corporate bond tokenization, blockchain infrastructure, and enterprise implementation planning. Visit Blocsys Technologies to discuss your roadmap and see how its platform approach can support a production-grade launch.
